Video Reports
Showing 47 results
-
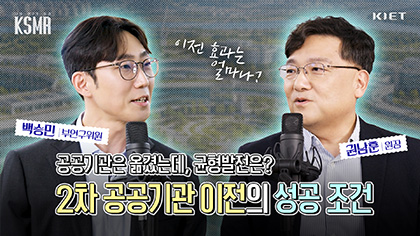
[Namhoon Kwon, president of the Korea Institute for Industrial Economics and Trade(KIET)]
Hello, everyone.
Today, we'll be introducing
one of our institute's most outstanding research reports.
The report we'll be covering today is titled
“The Impacts of the Public Sector Relocation Program and Policy Directions for Regional Hub Cities.”
The government has pursued balanced regional development for years now. As part of these efforts,
many public institutions have been relocated from the Seoul Capital Area (SCA) to Korea’s provincial regions. This report analyzes these initiatives.
Today, we're joined by Dr. Baek Seungmin,
who will walk us through the findings of the report.
Welcome, Dr. Baek, and thank you for joining us.
[Dr. Seungmin Baek, an Associate Research Fellow at KIET]
Thank you for having me, President Kwon.
I'd like to start by asking how this research came about.
The government began relocating public institutions out of Seoul quite a while back.
What prompted you to take on this study now?
As you mentioned, the public sector relocation program
actually got underway in 2012.
Counting Sejong City, the so-called Innovation Cities, and individual relocation destinations,
around 60,000 public-sector jobs moved out of the Seoul Capital Area (SCA),
making the relocation program one of the government’s flagship balanced regional development policies.
The first phase of the public sector relocation wrapped up in 2019, so a fair amount of time has passed since then -
and yet, the debate over whether the Innovation Cities and the relocation program
actually brought us closer to balanced development is still very much alive.
When you look at the data, in fact, population and economic activity
have continued concentrating in the SCA ever since 2000,
with the exception of the few years in the 2010s when relocation was most active.
It was this concern that led us to design this study -
to take a fresh look at the ripple effects of the public sector relocation policy.
Looking through the report, I see you examined
how moving public institutions out of the SCA affects
regional population, employment, and other indicators.
The big things we care about are population and employment. So, what kind of changes did you find, if any?
Well, for one, we found that the relocation of public institutions out of the SCA led to a substantial increase in population and employment
in the host regions that received those institutions -- the Innovation Cities.
And among the other findings of our analysis,
another interesting thing we observed was that
that the ripple effects of the relocation policy differ noticeably from industry to industry.
As public institutions relocated, we saw a clear rise in
service-sector employment in host regions
but not in manufacturing employment.
That’s an interesting result. I wonder: why did the effect show up in services, but not in manufacturing?
I’ll explain how the effects concentrate in the service sector
through two specific channels.
The first channel has to do with differences in tradability across industries.
Basically, manufactured goods like electronics or machine parts
can be sold to anyone, regardless of how far away they live from the factory.
Services, on the other hand - things like restaurant food and haircuts -
are much harder to sell to people that don’t live close to where the service is performed.
So when public institutions are relocated,
and a host region’s population, income, and consumption rise,
this difference in tradability
naturally concentrates spending on local, in-person services.
The second channel owes to a limitation inherent to the public sector itself.
Unlike private firms, public institutions produce public goods,
which aren't traded in the market to begin with,
and in producing them, these institutions have little incentive
to transact with other firms in the market.
I see. Another thing: This study didn't stop at the Innovation Cities themselves -
it also looked at how the economic effects spread to surrounding areas.
That’s what we usually call the “spillover effect.”
It looks like you analyzed that as well.
Well, as you’re aware, we're having this conversation in Sejong City right now.
The idea was that, as Sejong grew, nearby cities like Cheongju,
Gongju, and Daejeon would also reap benefits,
and grow along with Sejong. That’s the basic idea, I think.
Did your analysis actually pick up a spillover effect?
Yes, there was a spillover effect,
but it wasn't as large as we'd expected.
To be specific,
service-sector employment rose only slightly
within about 5 kilometers of the Innovation Cities,
and manufacturing employment showed only a marginal increase,
and only within roughly 10 to 15 kilometers.
The reason the spillover effect was smaller than expected
comes back to the same limitations I mentioned earlier -
the inherent limits of public institutions’ ability to generate broad ripple effects.
During the first round of the public institution relocation program,
public agencies were relocated out of the SCA to all kinds of places across the country.
I'd imagine the effects were stronger in some places than others -
I mean, it seems likely that that’s how it played out.
But what did your analysis actually say about how the outcomes differed by region?
To sum up the simulation results, the effects were quite heterogeneous.
Broadly speaking, the more populous a receiving region already was,
the larger the population gain it was expected to see.
And once we factored in accessibility to major cities,
the effects diverged clearly by industry.
For manufacturing, employment gains were largest
when institutions moved to mid-sized cities of 300,000 or more
that were close to major cities.
Conversely, when relocation went to smaller cities
far from major cities,
service-sector employment was expected to show a clear increase instead.
Well, taking in your findings, they seem to carry a lot of implications.
And this study couldn’t come at a better time, as there's been a lot of talk recently about a second round of public sector relocation.
That makes your findings especially useful -
for this second round of relocations.
So, in light of these findings, what approach would you recommend?
First, economies of scale come into play in public sector relocation -
meaning that the more people who relocate, the larger the effect tends to be.
So concentrating relocations
is one effective way to maximize their impact.
Second, conventional theories of urban growth tell us
that having industries that produce tradable goods - products that can be exported beyond the local market -
matters a great deal for a city's long-term growth.
Based on our findings, then,
I'd suggest that relocating to areas with very strong access to metropolitan infrastructure
and are moderately large cities in their own right
would be advantageous for building hub cities
by fostering the growth of tradable-goods industries such as manufacturing.
That said, I do want to add one caveat: the direct effect of public sector relocation
is bound to fade over time, no matter what.
So if the Innovation Cities are to grow, as originally intended,
into the regional-scale hub cities that can drive development across their wider region,
then, important as public sector relocation is to that growth,
it's even more important to design policies that amplify that effect and help prolong it.
All right, so what kinds of policies would you suggest? Just for example.
Above all, I think we need to build on the strengths the Innovation Cities already have.
To start, they're characterized by a high concentration of public institutions,
which gives them real potential to generate what's known as agglomeration economies -
the economic benefits that arise when firms and people cluster together.
I think that potential is considerable.
On top of that, compared to their surrounding areas,
Innovation Cities are newer, planned towns, and in general better places to live.
I think we should make good use of these strengths
and focus policy efforts on building agglomeration effects
over the long run.
For instance, compared to surrounding areas, Innovation Cities
are relatively well positioned to attract firms
or institutions with a higher share of skilled workers.
One option would be to help these institutions and firms cluster
within or around the Innovation Cities,
for example by offering them additional incentives.
Through sustained, long-term investment in infrastructure,
if we can narrow the livability gap between the SCA and Innovation Cities to some degree,
then population growth and firm inflows
could raise urban productivity, which would in turn drive further population growth -
and that virtuous cycle is what we'd expect to see.
And finally, for these policies
to work as intended, governance matters a great deal.
Direct support from the central government is certainly important,
but in the end, it's local governments that have to design and lead the Innovation Cities going forward, and
so their attention and investment really matter.
Thanks. So, to sum up what we've discussed today,
moving public institutions out of the SCA
has clearly succeeded in boosting regional population and employment.
But that effect fades over time,
and in some sense, falls short of some of original goals of the balanced development policy.
So that's one aspect we need to look at more closely.
And on how to turn this initial boost into sustained growth,
you've walked us through the range of factors we need to consider.
As the second round of public sector relocation is now underway,
attention shouldn't be limited to simply dividing up institutions
or deciding where to send them -
we need to analyze how to turn each region
into a genuinely sustainable growth hub.
I expect Dr. Baek's report to make a real contribution to that process.
Thank you again to Dr. Baek Seungmin
for taking the time to join us today.
Thank you for having me.
Thank you as well to everyone who joined us.
Next time, we'll be back with more in-depth, fascinating research.
Thank you.
-
What is the industrial outlook for Korea's 13 Flagship Industries: H2 2026
by the Korea Institute for Industrial Economics & Trade (KIET)?
Click 'Quality' on the video to watch in 1080p!
Check out the video for the outlook for Korea's 13 Flagship Industries: H2 2026(Machinery, Materials, and New IT Industries) for the upcoming second half of 2026!
00:05 Outlook for the 13 Major Industries in the Second Half of 2026
01:25 Export Outlook for the 13 Major Industries in the Second Half of 2026
06:13 Domestic Demand Outlook for the 13 Major Industries in the Second Half of 2026
07:43 Production Outlook for the 13 Major Industries in the Second Half of 2026
09:12 Import Outlook for the 13 Major Industries in the Second Half of 2026
11:44 Industrial Outlook Weather Map for the 13 Major Industries in the Second Half of 2026
For more details, please check the research report on the KIET website!
2026 H2 Economic and Industrial Outlook Report
https://www.kiet.re.kr/trends/ecolookView?ecolook_no=56&skey=&sval=
#KIET #2026 #SecondHalf #IndustrialOutlook #MajorIndustries #Exports #DomesticDemand #Production #Imports #Machinery #Materials #IT #Industries #Companies -
What is the Korea's Macroeconomic Outlook for H2 2026 as viewed
by the Korea Institute for Industrial Economics & Trade (KIET)?
Click 'Quality' on the video to watch in 1080p!
Check out the video for the economic situation (economic growth rate, private consumption, import/export outlook) and forecast for the upcoming second half of 2026!
00:03 Economic Situation in the Second Half of 2026
01:33 Domestic Economic Growth (GDP Growth Rate) in the Second Half of 2026
02:34 Internal and External Variables for Domestic Economic Growth in the Second Half of 2026
03:12 Private Consumption Outlook in the Second Half of 2026
04:04 Investment Outlook in the Second Half of 2026
04:42 Import and Export Outlook in the Second Half of 2026
For more details, please check the research report on the KIET website!
2026 H2 Economic and Industrial Outlook Report
https://www.kiet.re.kr/trends/ecolookView?ecolook_no=56&skey=&sval=
#KIET #2026 #SecondHalf #EconomicOutlook #Macroeconomics #ExchangeRate #Exports #OilPrices #Consumption #Investment #Economy -
Shifting global power dynamics
A tidal wave of global technological innovation
Korean industry has reached an inflection point.
It is time to move past mere survival,
and enter into a new phase of growth.
What are the key industries that will power our future?
Presented by the Korea Institute for Industrial Economics & Trade (KIET)
Korea's new industrial growth strategy…
revealed here.
The Next Leap Forward for Korean Industry: Challenges and Strategies
Part 1. Seizing Opportunities
① Semiconductors:
The Backbone of AI
Data centers are now the greatest source of demand for semiconductors, replacing mobile devices.
As major tech companies race to develop their own AI accelerators, the chip market is expanding at a remarkable pace.
This presents a major opportunity to strengthen the profitability and technological edge of Korea's memory chip makers.
Moreover, this shift is driven by geopolitical forces. Global OEMs are looking to move advanced semiconductor manufacturing outside of China, which opens the door
for late-comers in the foundry space, Samsung and Intel.
② Secondary Batteries:
Capturing Leadership in a Market Set toward Future Mobility and Physical AI
The battery industry sits at the heart of future mobility, decarbonization, and physical AI,
and carries exceptional growth potential.
While growth in the EV battery market has slowed, demand for energy storage systems (ESS) is surging.
ESS is vital to power grids and AI data centers, and over the long term the prospects for firms in this space are bright.
Korean battery firms possess world-class technology and mass production capabilities. Together, they constitute a robust foundation for leading the enormous battery market of tomorrow.
③ Biotechnology:
A Game Changer That Could Redefine Human Health
The biotech industry is undergoing a paradigm shift, led by cutting-edge fields like cell and gene therapy, which are projected to grow at over 19% annually.
The very shape of the industry is being redrawn.
As a key tool for tackling incurable diseases, global demand is set to rise, positioning biotechnology as a compelling new engine of growth.
④ Mobility:
From a Mode of Transport to a Living Platform
The automobile is no longer just a way to get from point A to B. It is evolving into a software-defined mobility platform.
Advances in electrification and autonomous driving are giving rise to entirely new forms of transport, from urban air mobility (UAM) to robotaxis.
These platforms are poised to pioneer new markets for on-demand, responsive mobility services.
By combining Korea's deep-rooted design and manufacturing expertise (built up over decades as an industrial powerhouse) and advanced IT capabilities,
Korea can take the lead across the entire mobility services value chain.
⑤Robotics:
Responding to Demographic Shifts and Manufacturing Innovation
Labor shortages driven by an aging and shrinking population are now a very real challenge facing Korean industry.
Advanced robotics is drawing attention as a key solution to that very problem.
The integration of AI and advanced ICT with robotics is driving transformation well beyond factory automation,
reshaping logistics, healthcare, and the broader service sector as well.
Ultimately, robotics is becoming a critical lever. Robots can help firms tackle labor shortages, improve working conditions, and drive up both productivity and industrial competitiveness.
⑥ AI
Artificial Intelligence:
The Infrastructure That Will Define Intelligence Across All Industries
AI is not only a high-value industry in its own right, but a general-purpose technology that is driving transformations across the entire economy.
Leading nations and corporations around the world have come to regard AI as a core national asset,
pouring focused investment into acquiring and advancing AI-based technologies.
Korea must harness its strong manufacturing and service-based economy to deploy AI technology
and build a virtuous cycle that simultaneously advances both AI and Korea’s flagship industries. Only by doing so can it hope to secure a defensible moat in the global arena.
The opportunity for Korean industry to rise again is real.
But the competitive pressure from abroad is intensifying by the day.
What matters now
is that Korea summons the willpower to seize the opportunities
of the current era to generate tangible growth.
Part 2. Strategies for Leading Tomorrow's Industries
① Semiconductors
Now, it comes down to speed.
In the face of aggressive subsidy campaigns from the US, China, and other rivals, Korea must make efforts
to level the playing field for its flagship chip companies.
In particular, securing and stabilizing production yields for sub-2nm advanced foundry processes at the earliest possible stage,
and achieving economies of scale, is the surest path to survival and market share growth for Korea's nonmemory semiconductor industry.
At the same time, there is a clear need to offer institutional support for infrastructure (especially water and power) and ease the 52-hour workweek restriction for R&D personnel.
By around 2030, the contours of the AI semiconductor race will come into clear view.
The time to act — and to act with policy support — is right now.
② Batteries
The battery industry is currently navigating a triple threat: an EV demand chasm, rising Chinese market share, and growing policy uncertainty.
If the industry fails to weather this polycrisis and its underlying fundamentals weaken, there is a real risk of ceding the vast future market to China and other competitors.
It is essential to secure and maintain a decisive competitive lead in next-generation technologies, such as solid-state batteries.
In this, the government's role is critical.
Stronger industrial policy is a plain necessity. Firms need help to navigate the current crisis and to lay the groundwork for the future.
Introducing domestic production incentive tax measures for battery cells and key materials would help companies survive through the downturn,
Expanded government R&D investment would help catalyze future readiness efforts.
③ Biotechnology
There is a pressing need to actively embrace AI-driven drug discovery. AI has been proven to cut development times and improve process innovation.
But perhaps even more importantly, Korea needs to produce capable convergent talent: physician-scientists who bridge medical knowledge and engineering expertise.
Ultimately, human resources will be the key to global competitiveness.
④ Mobility
In the mobility sector, Korea must move away from the closed, OEM-centric structure of the past and toward an open industrial ecosystem built on collaboration with technology companies.
Core software technologies like autonomous driving algorithms must be brought in-house, and the regulatory environment regarding data usage protocols and insurance frameworks must be proactively overhauled to facilitate commercialization.
Finally, building an integrated, central overseeing body capable of aligning policy in a coherent direction
will be essential if Korea is to stake out a lead in the future mobility market.
⑤ Robotics
For Korea's robotics industry to make the next step, it must first localize the production of critical components such as reducers, sensors, and controllers,
and build genuine technological self-reliance.
In the era of physical AI, field data is the lifeblood of competitiveness. Technology validation and data accumulation must go hand in hand with real-world pilot projects.
On top of that, promising robotics companies need targeted support
to help them scale up and successfully commercialize, with an eye toward becoming world-class niche champions.
Ultimately, building a structure in which key components, data, and innovative companies all grow together is what will propel Korea's robotics industry to the next level.
⑥ AI
Artificial Intelligence
To hold its own against the general-purpose LLM market dominated by global tech giants, Korea must develop
high-performance small language models and vertical AI technologies tailored to its own manufacturing environment.
This will deepen process intelligence and, leveraging its strong hardware capabilities, allow Korea to carve out a competitive edge in the next-generation on-device AI market.
To get there, parallel efforts in building industrial data feedback systems, developing domain-specific convergence talent, and establishing AI pilot special zones are all essential.
In an era of great transformation,
every crisis is an opportunity for Korea to rise higher.
When the drive for innovation and the power of strategic execution come together as one,
Korea's next golden age will begin.
In the bold journey into the future,
Korean industry stands at the vanguard.
-
[KIET 50th Anniversary Special Feature - Voiced from Abroad]
Ep.07 Barry Naughton
In celebration of its 50th anniversary,
the Korea Institute for Industrial Economics and Trade (KIET) is hosting a special interview series,
inviting world-renowned scholars to share their insights on the rapidly evolving industrial landscape and key global issues.
Our guest for this episode,
Professor Barry Naughton,
holds a Ph.D. in Economics from Yale University.
He is the author of several influential works,
including Growing Out of the Plan
and The Chinese Economy:Adaptation and Growth.
Currently, he serves as the So Kwanlok Chair of Chinese International Affairs
at the School of Global Policy and Strategy,
University of California, San Diego (UC San Diego).
In this video,
we discuss China Industrial Policy 3.0,
exploring China’s latest industrial and technological policies
as well as new forms of direct government intervention.
Watch the full interview to gain deeper insights into these transformative shifts.
00:15 Profile: Professor Barry Naughton
00:29 Evolution of Chinese Industrial Policy over the Last 20 Years
03:25 Contemporary Industrial Policies and Key National Champions
04:41 Motivating Ethos and Key Features of China IP 3.0
07:56 The Costs of China Industrial Policy 3.0
11:28 Reasons for Resisting the Transition to a Service-Oriented Economy
13:27 High-Tech Exports and the Belt and Road Initiative (BRI)
18:00 Implications of China IP 3.0 for South Korea
For more detailed analysis,
please refer to the full report available
on the Korea Institute for Industrial Economics & Trade (KIET) website.
#SouthKorea #China #Industry #IndustrialPolicy #Economy #Structure #Technology #Competition
-
[KIET 50th Anniversary Special Feature - Voices from Abroad]
Ep.06 Troy Stangarone
In celebration of its 50th anniversary,
the Korea Institute for Industrial Economics and Trade (KIET) has prepared
a special interview series to hear insights from world-renowned scholars
on the rapidly changing industrial landscape and key global issues.
Joining us for this episode is Troy Stangarone.
He is currently a Non-resident Fellow
at the Carnegie Mellon Institute for Strategy & Technology.
His distinguished background includes serving as Senior Director
at the Korea Economic Institute of America (KEI),
Co-Chair of the Steering Committee for the North Korea Economic Forum
at the George Washington University Institute for Korean Studies,
Director of the Hyundai Motor-Korea Foundation Center
for Korean History and Public Policy,
and Deputy Director of the Indo-Pacific Program.
Watch the video now for an in-depth dialogue on
how South Korea and Japan are navigating
and responding to U.S. trade agreements and tariffs.
00:15 Profile of Troy Stangarone
00:29 The Rise of Trump and the Retreat of U.S. Economic Openness
04:13 Differences Between Korea and Japan's Trade Agreements with the U.S.
07:14 Japan's Large-Scale Investments and Phased Execution Strategy
08:08 Benefits Korea Stands to Gain from the U.S.-Korea Agreement
12:24 The Future of the U.S.-Korea Trade Agreement Following U.S. Supreme Court Rulings
16:57 Does Foreign Investment in U.S. Manufacturing Provide a Foundation for Industrial Policy?
For more details, please read the full report on the KIET website!
#USA #DONALDTRUMP #KOREA #JAPAN #TRADE #AGREEMENT #TARIFF
-
[KIET 50th Anniversary Special Feature - Voiced from Abroad]
Ep.05 Barry Eichengreen
In celebration of its 50th anniversary,
the Korea Institute for Industrial Economics and Trade (KIET) is
hosting a special interview series,
inviting world-renowned scholars to share their insights
on the rapidly evolving industrial landscape and key global issues.
Joining us for this episode is Barry Eichengreen,
a Distinguished Professor at the University of California, Berkeley.
Professor Eichengreen served as a Senior Policy Advisor
at the International Monetary Fund (IMF) from 1997 to 1998
and is currently a Research Fellow
at both the National Bureau of Economic Research (NBER)
and the Centre for Economic Policy Research (CEPR).
Watch the video to hear his in-depth analysis of
the multi-layered economic
and geopolitical challenges Korea faces today—
from the retreat of globalization and the U.S.-China divide
to global financial volatility.
00:15 Profile of Professor Barry Eichengreen
00:29 The Retreat of Globalization: Why It's a Concern for Korea
03:38 Lessons Korea Learned from the 1997 Financial Crisis
06:25 Why Korea’s Service Sector Productivity Lags and How to Fix It
09:30 Strategic Choices for Korea Amidst the U.S.-China Rivalry
For more details, please read the full report on the KIET website!
#Globalization #Global #FinancialCrisis #Service #Productivity #Geopolitics #Innovation #Economy #Industry #Strategy
-
Core Industries in a Red Ocean: Is There a Way Out of the Crisis?
Three sturdy pillars have long upheld the Korean economy
petrochemicals, steel, and shipbuilding. These pillars are shaking.
From China’s indiscriminate flood of exports, to the formidable barrier of carbon neutrality,
to the rapidly shifting geopolitical landscape...
The time has come to fundamentally reassess the very framework of Korean industry.
The Structural Crisis of Korean Industry
Many view the current difficulties as a temporary economic downturn.
But the numbers tell a different story.
Korea’s manufacturing value-added ratio stands at 27.6%, stubbornly below the 30% figure in other major OECD economies.
We may have succeeded in producing things in large quantities, but we have much work to do in capturing commensurate value.
China rules the commodities market, and Korea is now feeling the squeeze.
The State of Korea’s Three Core Industries – Petrochemicals
In the past, the boom-and-bust cycle that dominates the petrochemicals sector was predictable.
But something has broken the cycle, and the industry has been trudging through a downturn for far too long.
The petrochemical sector’s key profitability indicator is known as the ethylene naphtha spread.
This number reached a nadir in the second half of 2022, almost four years ago, but has yet to recover.
The reason for this can be summed up in one word: China.
By 2022, China was already the world’s largest ethylene producer,
and is now on the verge of becoming entirely self sufficient in every stage of the ethylene value chain.
What was once Korea’s biggest customer has transformed into its most formidable competitor,
flooding markets with low-cost output.
Chinese ascendancy has had direct and deleterious effects on local Korean communities.
Local tax revenues from the Yeosu Industrial Complex (located near the southern coast of the country) are just half of what they once were.
This has set off a vicious cycle, with devastating effects on nearby commercial districts.
The State of Korea’s Three Core Industries – Steel
The year 2025 will go down as an especially painful one for Korean steel.
Domestic demand fell to its lowest level since 2002,
while surging electricity costs added further pressure, some steel plants run
by POSCO, Hyundai Steel, and Dongkuk Steel were forced to shut down or halt operations.
Cheap Chinese steel dumped onto the Korean market is a root cause of the problem, but weak domestic demand is another culprit.
Since the 2000s, China has rapidly scaled up steel production to the point where it now accounts for over half of global output.
The resulting oversupply has forced international prices into a tailspin, and Korean steelmakers have absorbed enormous losses in the process.
Adding to this, the second Trump administration has imposed steep tariff barriers on Korean steel exports.
The impact of the 50% steel tariff on U.S. imports will soon become fully apparent.
The EU too has signaled that it will cut import quotas significantly;
and there is also the Carbon Border Adjustment Mechanism to contend with.
The State of Korea’s Three Core Industries – Shipbuilding
The shipbuilding industry found itself in a prolonged slump following the 2008 global financial crisis.
Orders dried up and losses on foreign exchange derivatives forced many small and mid-sized shipyards to close.
From 2016 onward, losses on offshore plant projects and a continued order drought compelled even the major builders to undergo large-scale restructuring.
A crisis was readily apparent. But an opportunity for a rebound has emerged.
First, Korean shipbuilders maintained their competitive edge in high-value-added segments such as LNG carriers and eco-friendly vessels.
The global energy transition and shifting trade patterns have driven a surge in LNG demand,
while the maritime industry’s push for carbon neutrality has seen demand grow for green shipping options.
Second, favorable winds are blowing from the United States.
Korea’s proposed Korea–U.S. Shipbuilding Cooperation initiative, known as MASGA (Make American Shipbuilding Great Again),
played a significant role in reciprocal tariff negotiations with the U.S.
With its own shipbuilding capacity in decline, the U.S. urgently needs the expertise of Korea,
which possesses the world’s most advanced shipbuilding technology.
Through this bilateral cooperation, Korea’s shipbuilding industry expects to gain access to the U.S. as a major new market.
Three core industries that together constitute the beating heart of Korea’s export-driven economy are
showing signs of malaise, and the illness could spread throughout the national economy.
Korea once took pride in its global leadership, but many of its flagship industries have now been overtaken by China, or are on the verge of it.
What can Korea do?
If Korea’s core industries are to survive, they cannot rely on the strategies that led to prior successes.
They must either secure commanding technological leads or undertake bold business restructuring to pivot toward high-margin specialty products.
Leaving market forces to determine winners is no longer a viable option.
Around the world, governments are engaged in active policy competition to protect and advance their domestic industries.
Comprehensive support for upgrading the steel industry, including through the K-Steel Act, is urgently needed.
Japan has designated its shipbuilding industry as a national security asset,
The government is providing 1 trillion yen in support, describing the shipbuilding industry as one
that constructs vessels and warships to transport supplies and defend the nation in times of emergency.
Korea, too, needs to see shipbuilding and other core industries as more than just a line item on a spreadsheet.
These are major employers and exporters that are critical to national security.
To revitalize Korean manufacturing and strengthen industrial competitiveness,
we need to develop new growth paradigms and build collaborative systems aimed at upgrading the entire industrial ecosystem.
The government must play an active role in mitigating the risks of technological transition
and accelerating industrial transformation by calibrating R&D, infrastructure, and regulatory frameworks.
Korean industry – Don‘t just prepare for the future — make it. A crisis is an opportunity.
-
The First Crisis
Stalled Out: Weakening Industrial Competitiveness
The most obvious symptom of the Korean economy’s deteriorating health is the annual economic growth rate,
which now hovers in the 2% range, making the 5% rates posted just after the turn of the millenium seem mythical by comparison.
The Korean economy has, in other words, gotten real old, real fast.
And not just old, but ossified. How do we know this? Twenty years ago,
Korea’s main exports were semiconductors, cars, and chemicals.
Today, Korea’s main exports are...semiconductors, cars, and chemicals.
The economy lacks dynamism; there‘s no new blood circulating through its veins.
Over the past decade, the percentage of new market entrants has fallen to 6% from 9%;
market exits by incumbent firms also fell from 7% to 5% over the same period.
The patient not only has a weak heart, but a poor metabolism as well.
The Second Crisis
Cracks in the Facade: Declining Innovation Capacity
The patient looks weak. And the internals are in even worse shape.
The economy is plagued by numerous marginal enterprises,
or zombie firms, whose profits aren’t enough to pay the interest on their debts,
let alone the principal. Since the COVID pandemic, the number of marginal enterprises has skyrocketed.
The risk of widespread corporate insolvency is real and growing.
Having so much capital tied up in zombie firms hinders innovation.
Korea is considered an AI powerhouse,
but AI adoption rates in the country’s enormously important manufacturing sector sit at just 3.9%.
The Third Crisis
Storms Abroad: Upheaval in the Global Environment
To make matters worse, the playing upon which Korea achieved so much success — the global free trade regime — has been ripped out.
The Inflation Reduction Act (IRA) and the CHIPS and Science Act were the tools through
which the US did the deed. Both laws provide massive subsidies to firms that invest in the US.
This is why Samsung builds new factories in Texas and Hyundai puts up new production lines in Georgia instead of Korea.
And it would be a mistake to think of the current global trade environment has one of mere ’disputes.’ In 2023,
71% of all trade-distorting policies were promulgated by advanced countries that directly compete with Korea.
What we’re seeing is a fundamental transformation of the global industrial environment.
Korea was one of the first fast-followers and one of that model’s greatest success stories.
But it no longer represents a viable survival strategy.
Another issue: The green transition is coming and Korea is not ready for it.
The European Union (EU) Carbon Border Adjustment Mechanism (CBAM) is imminent,
but Korea’s energy mix remains dominated by fossil fuels, with renewables account for just 9.5% of power generation.
This lags far below global leaders like Germany (57.3%) and even China (32.6%).
Four Strategies for Tackling Korea’s Industrial Crisis
Strategy 1: AI and the Green Economy
We propose four strategies for tackling Korea’s multifaceted industrial crisis.
The first: embrace the AI-powered future.
It will not be enough to merely adopt new technology: Korean firms need to address real world-problems using AI solutions.
For example: wearable robotics embedded with AI tech for use in the construction sector and other industries
that are now suffering from a major shortage of skilled workers.
The same goes for green technologies. For POSCO, Hyundai, or any other major steelmaker to spend billions to convert
their pollution-intensive blast furnaces to more eco-friendly solutions (hydrogen-reduction, for example),
the government would have to implement Carbon Contracts for Difference (CCfDs)
or some other mechanism in order to offset risk and get companies moving down the path of decarbonization.
Strategy 2: Policy Reform
Among other things, Korea’s industrial innovation system is in need of a major overhaul,
and this has to start with a change in the industrial R&D ecosystem.
Rather than being misled by the ostensible 90% success rate,
industrial R&D should be assessed on the basis of their real market outcomes.
Industrial innovation is what happens when technologies achieve success in the market.
Korea also needs to completely reconsider its approach to attracting investment.
Successfully attracting investment requires a mix of tax incentives, financial subsidies, and human resources support.
Currently, these functions fall under the purview of different ministries.
This dispersed and opaque system makes attracting large-scale investment from global firms extremely difficult.
The country also needs to shift refocus its investment attraction efforts from firms to projects.
Korea should make every effort to participate in projects led by global leaders;
this will help build out entire industrial ecosystems in Korea, rather than just individual firms.
Another thing to consider: Korean firms make a lot of money overseas,
but currently have little incentive to repatriate this money and reinvest profits in Korea.
The government needs to see capital repatriation as a kind of capital “reshoring,”
and offer benefits commensurate with those extended to foreign firms investing in Korea.
As for the country’s zombie firms, the solution is not to simply let them close their doors forever.
The government needs to let firms capable of growing realize their potential by allowing them to divest unprofitable
or low-value-added lines of business and shift to newer or more promising ones.
Policies that enable this can create new engines of economic growth,
but will require proactive and attentive policy support.
As for the regulatory regime, well — reform requires a top-down approach.
We need to analyze and reform laws and policies that act as constraints on entire industrial sectors.
Regulatory reform should be done on a case-by-case basis.
We should seek to make improvements to individual statutes to maximize regulatory consistency
and predictability and drive tangible change at the country’s businesses.
Strategy 3: Recalibrating Korea’s Foreign Policy
Next up: Korea also needs to rethink its global strategy.
For one, it needs to expand and strengthen cooperation with the US in critical strategic industries like biotech and semiconductors.
And when it comes to China, Korea should pursue a bifurcated strategy.
In areas where we still have the advantage, it is crucial that we maintain a super-gap with the Chinese competition.
In other areas, it is best to take a more pragmatic approach, and determine
where Korean firms can leverage the Chinese market and advanced manufacturing supply chains,
seeking out collaborative opportunities in segments where they are competitive.
For example, Korean suppliers could look to sell advanced electrical components to the Chinese EV sector.
Strategy 4: Upgrading Key Industries and Fostering Future Growth
Finally, Korea must address two other major challenges simultaneously.
The country must help its incumbent industries climb up the value-added ladder
while at the same time fostering an ecosystem that can create the next Samsung or Hyundai.
This is a daunting task. It’s like building a new ship while navigating a storm on the old leaky boat.
But we live in extraordinary times, and seeing Korean industry through the storm will require marshaling every resource available.
-
(Intro)
Hello. My name is Kyung-in HWANG, Director of the Office of Public Relations and Media at the Korea Institute for Industrial Economics and Trade (KIET).
As KIET marks its 50th anniversary, we are hosting a series of dialogues with leading international scholars
in which they share their insights on rapidly changing industrial conditions and major policy issues.
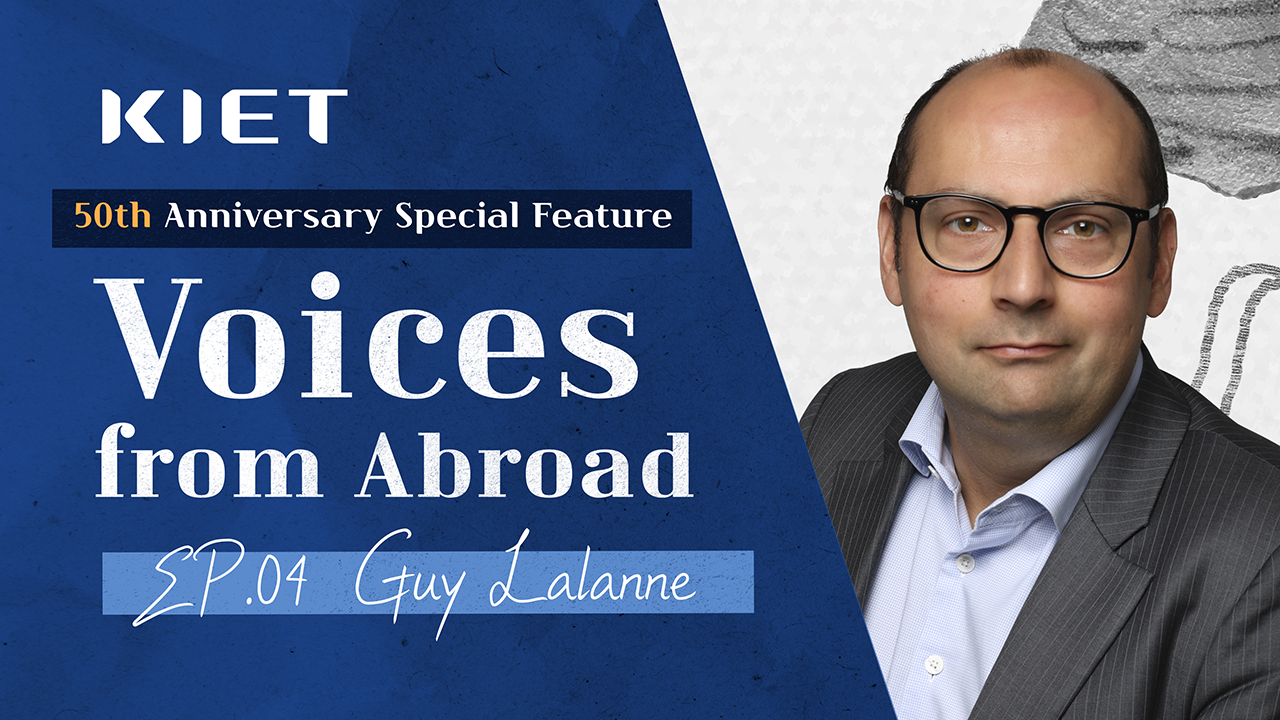
Today, we will be speaking with Dr. Guy Lalanne, Acting Head of Division — Productivity, Innovation,
and Entrepreneurship at OECD Directorate for Science, Technology and Innovation.
Lalanne previously served as Deputy Director of the Macroeconomic Forecasting Division
and the Business Policy, R&D and Innovation Division at the French Ministry of Finance.
Q1.
We understand the OECD recently built a database called QuiS,dedicated specifically to industrial policy.
Could you explain the background behind this initiative?
Q2.
Many countries are pursuing industrial policy on a significant scale, leading some to declare that we have entered a new era of muscular industrial policy.
However, in your contribution to IER, you note how the number of announced policies far exceeds the number of policies that have been actually implemented.
Are we really in a new era of tough industrial policy?
Q3.
In terms of policy instruments, direct fiscal support has been increasing, while the use of financial instruments (such as the creation of funds) appears to be declining.
What do you think is driving countries to choose this particular mix?
Q4.
Another notable feature is that once industrial policies are introduced,
they tend to persist over long periods without sunset clauses or termination, regardless of their effectiveness.
What do you see as the underlying cause of this tendency?
Q5. Looking at the areas receiving support, there has been a sharp increase in spending on the green transition, SMEs, and rising energy costs.
In your view, which of these areas is most likely to contribute to long-term productivity growth?
(Outro)
So far, I have been talking with Professor Guy Lalanne.
The 50th Anniversary Special Project: Dialogues with International Scholars will continue in the future,
so please show your interest and watch.
Thank you.
Please enter the security text below
to prevent email collection
Please check the information of the person in charge.